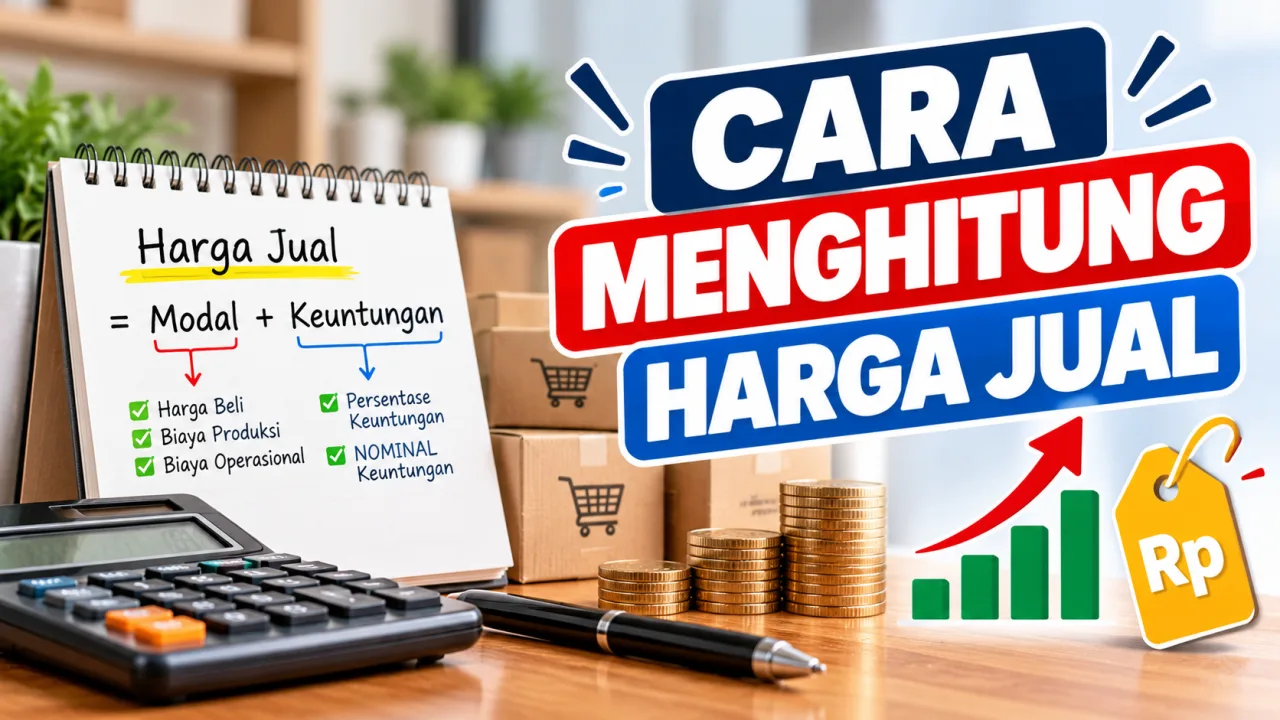
Determining product selling prices is not enough by just adding a profit on top of the capital price. If all incurred costs are not calculated correctly, a profitable-looking price might actually not cover all expenses yet.
Therefore, before setting a selling price, business owners need to know the costs actually incurred to produce or obtain a product.
A simple method that can be used is to calculate the cost per product first, then determine the profit to be obtained.
What is Meant by Selling Price?
Selling price is the value customers must pay when purchasing a product or service.
Meanwhile, product cost or capital is all expenses related to that product. In manufacturing businesses, costs can include raw materials, direct labor, and other production costs.
Therefore, calculating selling price based only on raw material prices can make profit calculation less accurate.
What Costs Need to Be Calculated?
Before determining the selling price, make a list of all costs related to the product. Some costs that are often forgotten include the following.
1. Raw Materials
Raw materials are the main materials used to make products.
For example, a food business uses flour, sugar, oil, eggs, spices, and other additional ingredients. For non-food businesses, raw materials can be fabric, wood, plastic, electronic components, or other materials.
2. Packaging
Packaging is often considered a small cost so it is not included in the calculation.
In fact, if a product uses a box, plastic, label, sticker, ribbon, bottle, or special packaging, all of these costs still affect the capital per product.
3. Labor
i economics.
In businesses that use employees or piece-rate labor, labor costs can be calculated based on the cost portion allocated for each product.
4. Electricity and Production Costs
Production equipment requires electricity, gas, water, or fuel. These costs can be allocated based on the number of products made in a certain period.
5. Equipment Depreciation
Equipment such as machines, ovens, printers, computers, production tools, or vehicles is not used only once.
The value of using such equipment can be allocated as a cost during its usage period so the product price is not too low.
6. Sales Costs
For sales through marketplaces or certain platforms, there may be administration fees, commissions, or other fees deducted from transactions.
These costs need to be calculated if you want to know the net profit from sales.
Example of Calculating Product Selling Price
For example, someone makes as many as 100 units of products in one period.
The total costs incurred are as follows:
| Cost Component | Amount |
|---|---|
| Raw materials | Rp2.000.000 |
| Labor | Rp500.000 |
| Packaging | Rp200.000 |
| Electricity and production | Rp150.000 |
| Other costs | Rp150.000 |
| Total cost | Rp3.000.000 |
If the production amount is 100 units, then the average cost of each product is:
Rp3.000.000 ÷ 100 = Rp30.000
Thus, the cost that must be covered from each product is around Rp30.000.
This figure does not automatically become the selling price because the business owner still needs to determine the profit to be obtained.
How to Determine Selling Price Based on Target Margin
For example, the cost per product is Rp30.000 and the target profit margin based on the selling price is 20%.
The formula that can be used is:
Selling Price = COGS ÷ (1 − Margin)
With that example:
Rp30.000 ÷ (1 − 20%)
Rp30.000 ÷ 0,80 = Rp37.500
So, the selling price with a 20% target margin is around Rp37.500 per product.
Margin and Markup Are Not the Same
Margin and markup are often used interchangeably, even though both have different calculation bases.
Markup is calculated based on cost or COGS, while margin is calculated based on selling price.
These differences need to be noted because a certain markup target does not automatically produce a margin with the same percentage.
The mistake of distinguishing margin and markup can make expected profits not match actual results.
Don't Forget to Calculate BEP
Besides determining the selling price, business owners can also calculate the Break Even Point (BEP).
BEP shows the condition when revenue is able to cover costs so the business has neither made a profit nor a loss.
One BEP formula in units is:
BEP = Fixed Costs ÷ (Selling Price per Unit − Variable Cost per Unit)
For example:
- Fixed costs: Rp2.000.000
- Selling price: Rp40.000
- Variable cost per unit: Rp25.000
Then:
Rp2.000.000 ÷ (Rp40.000 − Rp25.000)
= 133,33 units
Since product quantities are usually whole numbers, the business needs to sell about 134 units to reach the break-even point based on that calculation example.
Why Selling Prices Should Not Be Based Solely on Competitor Prices
Looking at competitor prices is indeed useful to know market conditions. However, competitor prices do not always show how much cost they incur.
A product can be sold cheaper because it has larger production volume, lower operational costs, different suppliers, or certain business strategies.
Therefore, market prices should be used as a comparison, not as the sole basis for determining prices.
Calculating costs yourself is still necessary so business owners know the price limit that still makes sense.
Checklist Before Setting Selling Price
Before setting product prices, recheck the following components:
- Raw material prices have been calculated.
- Packaging costs have been included.
- Labor has been accounted for.
- Electricity or production costs have been accounted for.
- Equipment depreciation has been considered.
- Marketplace or transaction fees have been checked.
- Discounts and promotions have been calculated.
- Profit targets have been determined.
- Prices have been compared with market conditions.
- BEP has been calculated.
By making these calculations completely, the risk of setting prices too low can be reduced.
Conclusion
How to calculate product selling prices without losing money starts from knowing all costs incurred, not just material prices or purchasing prices of goods.
Once the cost per product is known, business owners can determine selling prices based on target margins or markups. BEP calculations can also be used to find out how many products need to be sold so business costs can be covered.
A good price is not merely a price that looks cheap to customers, but a price that still allows businesses to cover costs and earn reasonable profits.